Why Data Centre Work Is a Different Risk for Tradies
Rapid growth in complex builds is putting contracts, liability caps and specialist cover under sharper scrutiny
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
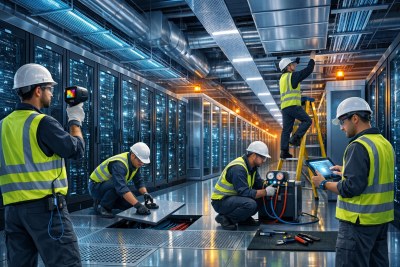
Australia’s fast-growing data centre construction market is opening opportunities for electrical, HVAC, fire protection, cabling, fit-out and commissioning trades, but recent insurance industry discussion suggests the risk settings are not always keeping pace with the work.
At a recent Australasian Professional Indemnity Group conference, specialists warned that data centre projects can involve unusual contractual, professional and technology-related exposures, especially where contractors rely on annual insurance programs designed for more conventional building work.
The issue is not that every trade business should avoid data centre jobs. Rather, these projects can be materially different from a standard commercial fit-out or industrial installation. They often involve high-value equipment, strict completion milestones, complex power and cooling systems, live operational environments and multiple parties whose work overlaps. A minor error during design, installation, testing or commissioning may have consequences beyond the immediate physical damage.
For tradespeople, the practical lesson is that insurance should be checked against the actual contract and scope of work, not just the business description on a renewal schedule. Public liability may respond to some third-party injury or property damage claims, but it may not address design advice, professional errors, technology failures, delay penalties or broad contractual indemnities. Similarly, project insurance arranged by a head contractor or principal should not be assumed to protect every subcontractor in every circumstance.
Check whether the contract requires specific limits for public liability, professional indemnity or contract works insurance.
Look closely at liability caps, indemnities and whether insurance proceeds reduce or sit on top of contractual exposure.
Identify any design, specification, programming, integration, testing or commissioning advice that could create professional indemnity considerations.
Confirm whether work will occur around live systems, server equipment, battery storage, generators, cooling plant or building management systems.
Keep written records of scope changes, client instructions, test results, handover documents and subcontractor responsibilities.
There are limits to what can be concluded from industry conference commentary. Market appetite, policy wording and contract terms vary, and larger data centre projects often involve specialist advisers on both the construction and insurance sides. However, the warning is useful for smaller trade businesses moving into higher-value technical projects: a bigger contract can also mean a bigger gap between what is insured and what has been promised.
Before accepting this type of work, trade businesses may wish to compare the project documents with their current policies, note any exclusions or sub-limits, and seek qualified advice where the contract transfers risks that appear wider than the insurance in place. In a sector built around uptime, redundancy and precision, a careful insurance review is part of the job preparation, not an administrative afterthought.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
New Zealand’s latest insurance dispute figures are a timely warning for anyone relying on personal cover to protect their household income. The Insurance & Financial Services Ombudsman Scheme reported that, for the year ended 30 June 2026, health insurance became the largest category of disputes it investigated for the first time, with health disputes up 91 percent and 833 dispute investigations completed across all categories. - read more
Fresh commercial insurance market data is giving Australian businesses a more favourable pricing backdrop, but truck owners should be cautious about assuming broad rate falls will automatically reduce heavy vehicle premiums. Marsh’s Q3 2026 Global Insurance Market Index, released on 21 October 2026, reported a 12 per cent fall in Pacific commercial insurance rates for the quarter, led by property and supported by strong insurer competition and available capacity. - read more
Australia’s fast-growing data centre construction market is opening opportunities for electrical, HVAC, fire protection, cabling, fit-out and commissioning trades, but recent insurance industry discussion suggests the risk settings are not always keeping pace with the work. At a recent Australasian Professional Indemnity Group conference, specialists warned that data centre projects can involve unusual contractual, professional and technology-related exposures, especially where contractors rely on annual insurance programs designed for more conventional building work. - read more
Australia’s life insurance industry has moved mental health cover back to the centre of the affordability debate, after the Council of Australian Life Insurers released its response on 30 September 2026 to the independent review of the Life Insurance Code of Practice. For workers who rely on income protection insurance, the issue is practical: mental health conditions can affect earning capacity just as seriously as physical illness, but changes designed to keep premiums manageable may also alter what is covered. - read more
The 2026 National Truck Accident Research Centre major incident report gives Australian truck operators a useful, if challenging, snapshot of where serious heavy vehicle risk is changing. Released in October 2026 and based on de-identified NTI-insured heavy vehicle major-loss claims, the report points to progress on distraction and fatigue, while also highlighting renewed concern about inappropriate speed and following distance. - read more
Cyber insurance, also known as cyber liability insurance, is a type of coverage designed to protect businesses from the financial repercussions of cyber attacks and data breaches. As cyber threats become more sophisticated, the need for a safety net to mitigate the impact of such incidents has grown significantly. - read more
Australian businesses that experience a data breach may need to assess whether the Notifiable Data Breaches scheme applies, notify the OAIC and affected individuals, report cybercrime through ReportCyber, and carefully document their response. This guide explains the key notification and reporting steps in general terms, and how cyber insurance may support breach response planning. - read more
Cyber insurance premiums for Australian businesses can vary because insurers assess each business's data exposure, industry, systems, security controls, claims history and selected cover. This guide explains the main factors that may influence cost and how SMEs can prepare for a clearer quote process. - read more
Cyber risk management involves identifying, assessing, and prioritizing potential risks to an organization's digital assets and implementing measures to mitigate these threats. - read more
In an age where digital presence intertwines with daily operations, the threat landscape in Australia has magnified, exposing businesses to an evolving array of cyber threats. From sophisticated phishing attempts to ransomware attacks, the risk of digital insecurity looms large. Australia, with its growing technological adoption, finds itself facing an upsurge in cyber threat incidents year over year. - read more
Knowledgebase
Insurance Deductible: the amount that an insured is required to contribute toward an insurance claim as stipulated in an insurance policy. Otherwise known as the "policy excess".


No comments yet. Be the first to share your thoughts.